The strategic case for the acquisition
Valley National Bank’s planned $340 million purchase of Bluevine would give the bank a scaled digital small business banking platform and a team of about 180 focused on research and development. The acquisition, expected to close in early 2027, could spare Valley years of internal work to build comparable capabilities. That’s the strategic promise, not yet a demonstrated outcome: the platform’s value will depend on how much of its speed and operating discipline survives inside a larger bank. Tearsheet’s feature examines the challenge of bringing a fintech into a bank while retaining the capabilities that drove its growth.
For Valley, buying an established operation may be faster than assembling one product by product. But a transaction doesn’t automatically transfer the habits, technical choices, or customer understanding behind a digital business. Those are harder to measure than a platform or a team, and they’re often the parts that determine whether an acquisition delivers more than a change in ownership.
What each side brings
Bluevine contributes nationwide digital banking, customer acquisition, and technology spanning banking, lending, risk systems, and core infrastructure. Valley brings its balance sheet, banking capabilities, and more than 220 branches, giving Bluevine customers access to a broader set of resources. The deal’s potential rests on combining those strengths without slowing the platform Bluevine has built. That’s a real integration problem: the bank needs to connect the businesses while avoiding changes that make the digital operation less useful to the small businesses it serves.
The assets are complementary, but complementarity on paper isn’t the same as an effective operating model. Valley’s branches and balance sheet represent capabilities Bluevine can draw on, while Bluevine’s technology and customer-acquisition work may offer Valley ways to reach and serve businesses digitally. Each side will need clarity about which systems and decisions stay close to Bluevine and which are brought into the bank’s broader processes. If those boundaries are poorly handled, the combined organization could inherit complexity rather than create an advantage.
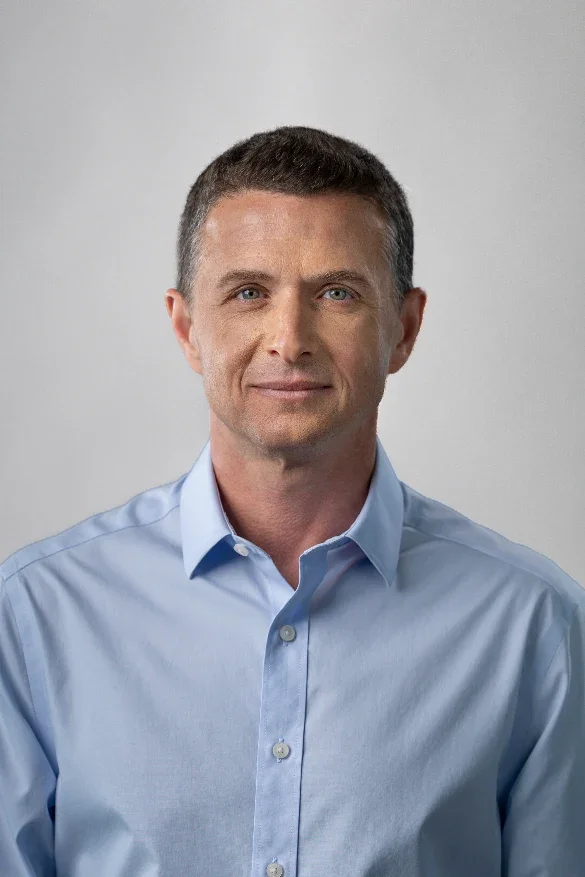
Tearsheet Managing Editor Sara Khairi spoke with Bluevine CEO Eyal Lifshitz about what should endure through the transition. Lifshitz is expected to lead Small Business Banking at Valley after the planned close, giving him a role in the integration as well as the business he has helped build. He discussed preserving Bluevine’s culture and extending its technology’s use across the bank. Those goals point to two different tests: retaining the conditions that helped Bluevine operate effectively, and making its capabilities useful beyond its existing business.
What Valley is buying beyond products
Q: Which Bluevine capabilities would have been harder or slower for Valley to build on its own? The question gets at the difference between acquiring a tool and acquiring an operating capability. For a bank, the latter can include the customer relationships, technical systems, and specialized experience needed to make products work together at scale.
Eyal Lifshitz, CEO of Bluevine: “What Bluevine brings is less about any single product or capability and more about the combination it has built at scale: a nationwide digital small business banking platform, a proven customer-acquisition engine, a full-stack banking and lending platform including sophisticated core elements, risk systems, and small business expertise.”
Lifshitz’s answer emphasizes the bundle rather than any one feature. That distinction matters because individual products can be copied or connected, while a functioning platform depends on coordination among technology, risk, lending, and customer acquisition. It also sets a demanding standard for the integration: Valley isn’t simply buying software; it’s taking on a system of capabilities whose value depends on how well they work together.
Integration is the test
The combination is the point: Valley gets an established digital operation, while Bluevine gains the reach and banking resources of a larger institution. How well the two fit together will shape the value of the deal after closing. This is more significant than it looks, because the benefits described by both sides are linked to execution rather than to the transaction alone.
In bank-fintech integrations, the organization has to reconcile different ways of building, maintaining, and approving products. A bank’s processes may support oversight and consistency, while a fintech’s operating model may be designed around faster product development and direct digital service. Neither approach automatically wins; the practical question is whether the combined company can protect essential controls without adding friction that undermines the customer experience. And this is the part most people overlook: a platform can remain technically intact while its ability to respond quickly is gradually constrained by new dependencies and approval paths.
Culture is not a soft side issue in that calculation. It can influence how teams make decisions, how they spot problems, and whether technical staff can keep improving systems after the acquisition. Lifshitz’s expected leadership role may help preserve continuity, but a title alone can’t settle questions about authority, priorities, or how Bluevine’s team will work within Valley. The actual arrangements will matter more than the rhetoric around integration.
What to watch after closing
The acquisition’s expected close in early 2027 leaves the central questions open for now. Readers should distinguish the announced strategic rationale from evidence that the combination is working: whether Bluevine’s digital platform remains effective, whether Valley can extend its technology across the bank, and whether customers can access the broader resources described in the deal. The source provides no detailed implementation plan, so claims about precisely how those changes will happen would be premature.
If you’re working in this space, the useful comparison isn’t simply digital banking against branch banking. It’s the capabilities each side can contribute, and whether the combined organization can make them reinforce one another. Bluevine brings a platform and specialized expertise; Valley brings institutional resources and physical reach. The purchase price and planned timing establish the scale and timetable of the transaction, but they don’t answer whether the operating model will preserve what made Bluevine valuable.
For Valley, the opportunity is to acquire a developed small-business operation rather than build every component internally. For Bluevine, the opportunity is access to a larger bank’s resources and reach. The risk is that integration consumes the very advantages the deal is meant to add. A promising fit, then. The hard work comes next.
The post How Bluevine will change under Valley Bank without losing its core appeared first on Tearsheet.


